
A reliable CD rate calculator is the single best tool you can use to watch your hard-earned savings grow safely over time. When you place your money into a certificate of deposit, you lock in a guaranteed interest rate for a set number of months or years. Using a CD rate calculator helps you discover exactly how much money you will earn before you ever open an account. It takes away all the confusing guesswork and shows you the total payout in simple, clear numbers. Because banks offer many different terms and interest rates, this tool helps you compare your best options in seconds so you can build strong, risk-free wealth for your future.
What Is a CD Rate Calculator and How Does It Work?
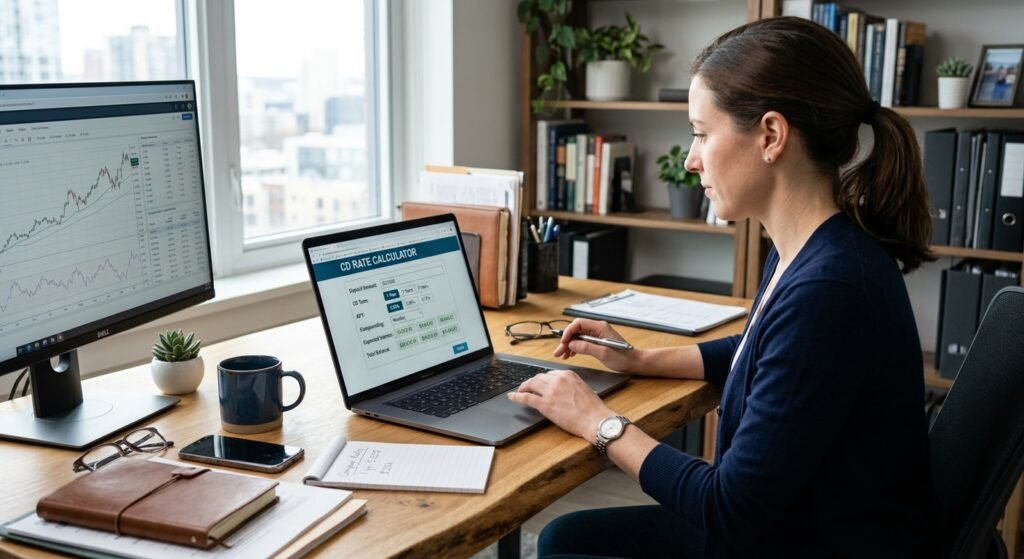
A CD rate calculator is a free digital tool designed to estimate your total financial returns on a certificate of deposit. You simply enter the amount of money you want to invest, the annual percentage yield, and the total time length of the deposit term. The online tool then uses simple mathematical formulas to compute your exact interest earnings instantly. It shows you precisely how much money you will have when your deposit term reaches maturity. By using this dynamic tool, you can test different money amounts and timeframes to see which high-yielding financial plan fits your personal savings goals best.
Why You Should Calculate Your Earnings Before Investing
Calculating your expected returns before opening a bank account gives you total control over your financial journey. Many people lock away their cash without realizing how much money they are actually going to make in return. When you compute your savings growth beforehand, you can set clear financial goals for your family. You can easily compare dynamic certificates of deposit against normal high-yield savings accounts to see which option offers better overall returns. This smart planning habit ensures that every dollar you save works as hard as possible to deliver continuous, reliable interest profits over time.
Understanding the Difference Between Interest Rate and APY
Understanding the difference between an interest rate and the annual percentage yield is essential for smart saving. The basic interest rate shows the simple percentage of money a bank pays you on your principal deposit every year. The annual percentage yield, or APY, is much more powerful because it includes the effect of compounding interest. Compounding interest happens when you earn fresh interest on top of the interest you already made previously. Because APY reflects your true total return over a full year, you should always look at the APY number when comparing different bank offers.
How Compound Interest Accelerates Your Money Growth
Compound interest is the secret engine that powers serious long-term growth inside a high-yield certificate of deposit. When your bank calculates your interest daily or monthly, that new money gets added right back into your account total. Your next interest payment is then calculated on this new, larger balance, creating a compounding growth snowball effect. Over time, even modest interest rates can transform standard savings into a surprisingly large sum of extra cash. Choosing a deposit account that compounds interest daily instead of annually will always maximize your final payout and grow your money faster.
Step-by-Step Guide to Using a CD Rate Calculator
Using a CD rate calculator is extremely easy and takes less than two full minutes to complete online. First, type in your initial deposit amount, which is the total dollar figure you plan to lock away inside the account. Second, enter the annual percentage yield offered by the financial institution you are considering for your money. Third, select the exact duration of the investment, such as six months, one year, or five years. Finally, click the calculate button to see your total earned interest alongside your final balance total.
Estimated Earnings Comparison Table
Here is a simple example table showing how a standard $10,000 initial investment grows across various deposit terms and annual percentage yields.
| Deposit Amount | Annual Yield (APY) | Term Length | Total Interest Earned | Final Account Balance |
| $10,000 | 4.00% | 1 Year (12 Mos) | $400.00 | $10,400.00 |
| $10,000 | 4.50% | 2 Years (24 Mos) | $920.25 | $10,920.25 |
| $10,000 | 5.00% | 3 Years (36 Mos) | $1,576.25 | $11,576.25 |
| $10,000 | 4.25% | 5 Years (60 Mos) | $2,313.47 | $12,313.47 |
Note: The figures in this table assume interest compounds daily and remains inside the account until maturity.
Comparing Short-Term Certificates Against Long-Term Certificates
Deciding between a short-term certificate and a long-term certificate depends heavily on your upcoming financial plans. Short-term deposits, like those lasting three to twelve months, give you fast access to your cash in the near future. They are great choices if you think national interest rates will rise soon or if you need money for upcoming expenses. Long-term deposits, such as four or five-year options, let you lock in strong interest rates for many years. This protects your guaranteed yield even if market interest rates drop significantly across the broader economy.
How Early Withdrawal Penalties Impact Your Overall Returns
Before opening any fixed account, you must carefully consider the potential costs of early withdrawal penalties. Banks put these steep fee penalties in place to discourage depositors from pulling cash out before the term ends. If you withdraw your money early, the bank may take away several months of earned interest, or even a small portion of your principal. Using a CD rate calculator helps you plan your term length realistically so you never have to pay these unwanted fees. Always maintain a separate emergency cash fund in a regular account so your fixed deposit stays safe.
The Strategy of Building a Strong CD Ladder
A certificate ladder is a brilliant savings strategy that offers both steady interest profits and regular liquidity. To build a ladder, you divide your total savings into equal parts and open several accounts with different maturity dates. For example, you might open one-year, two-year, three-year, and four-year certificates all on the same day. As each short-term account matures every single year, you get cash back or choose to reinvest it into a new long-term account with top rates. This clever approach provides flexible cash flow while constantly capturing high interest yields for your growing portfolio.
Key Factors to Consider Before Opening a Certificate Account
Choosing the right financial institution requires looking at several important features beyond just the advertised interest rates. You should always verify that your prospective bank or credit union is fully backed by federal deposit insurance programs like the FDIC or NCUA. Federal insurance keeps your money completely safe up to standard legal limits, even during tough economic times. Additionally, check the minimum initial deposit requirements to ensure they fit your current budget comfortable. Finally, read the fine print regarding automatic account renewals so you retain total control over your funds when the term finishes.
How National Inflation Affects Your True Investment Returns
When evaluating your long-term savings strategies, it is critical to keep the continuous impact of national inflation in mind. Inflation measures how fast the general costs of consumer goods and services rise over time across the economy. If your account’s annual percentage yield is higher than the rate of inflation, your money gains true purchasing power over the years. However, if inflation runs higher than your interest earnings, your cash actually buys less in the future despite growing in total dollar balance. Running calculations through a CD rate calculator helps you choose high yields that easily beat inflation.
Real-Life Example: How Sarah Maximized Her House Down Payment
Consider the real-life story of Sarah, a saver who wanted to buy her first home within two years. She saved $20,000 and wanted to keep it completely safe from stock market drops while still earning good growth. Sarah used an online CD rate calculator to compare a two-year fixed account yielding 4.80% against a standard bank savings account paying 0.50%. The calculation revealed she would earn over $1,900 in safe interest with the certificate, compared to under $200 at her local bank branch. She locked in the fixed rate, kept her home money secure, and bought her dream house right on schedule.
Frequently Asked Questions
What happens to my money when my account matures?
When your certificate matures, the bank opens a short grace period, usually lasting around ten days. During this temporary window, you can freely withdraw your initial money plus all earned interest without paying any penalty fees. You can also choose to roll the total balance into a brand new term or move it to a different bank.
Can I deposit more cash into my account later?
Most traditional fixed accounts do not allow you to add extra funds after your initial opening deposit is completed. Your locked rate applies only to the starting amount for the agreed term length. If you want to invest more money later, you can simply open a separate certificate account with its own current interest rate.
How often does interest compound in a typical certificate?
Interest compounding schedules vary depending on the specific rules of the issuing bank or credit union. Most top financial institutions compound interest daily or monthly, which builds your total balance faster over the term. Checking your account details in advance ensures you get the absolute best compounding frequency possible for maximum personal growth.
Are my interest earnings from these accounts taxable?
Yes, the interest you earn from a certificate of deposit is considered taxable income by the federal government. Your bank will send you an official tax form at the end of every year showing your total earned interest. You must report this money on your annual income tax returns, even if you keep the interest inside the account.
Is my money completely safe in a certificate of deposit?
Your money is exceptionally safe as long as you choose a federally insured bank or credit union. Accounts at insured banks are fully protected up to $250,000 per depositor, per ownership category. This ironclad government backing guarantees that you will never lose your principal deposit or earned interest, even if the bank fails.
Can I lose money if I use a CD rate calculator?
No, using a CD rate calculator is simply an online estimation process that carries zero risk to your personal finances. The calculator helps you visualize potential gains so you can make informed, smart choices before spending a single dollar. It gives you the clear foresight needed to pick winning financial products with absolute peace of mind.
Take Control of Your Financial Future Today
Taking control of your personal savings journey starts with making smart, informed choices about where to store your money. A CD rate calculator provides the clarity and confidence you need to select top-performing deposit accounts that match your exact life goals. By locking in high yields today, you protect your hard-earned cash from market swings while earning steady, predictable income effortlessly. Do not let your money sit idle in low-paying accounts when simple tools can help you unlock superior growth right now. Take a moment today to run your numbers, compare your options, and secure a brighter financial future.